
 Facebook
 X
 Pinterest
 Copy Link
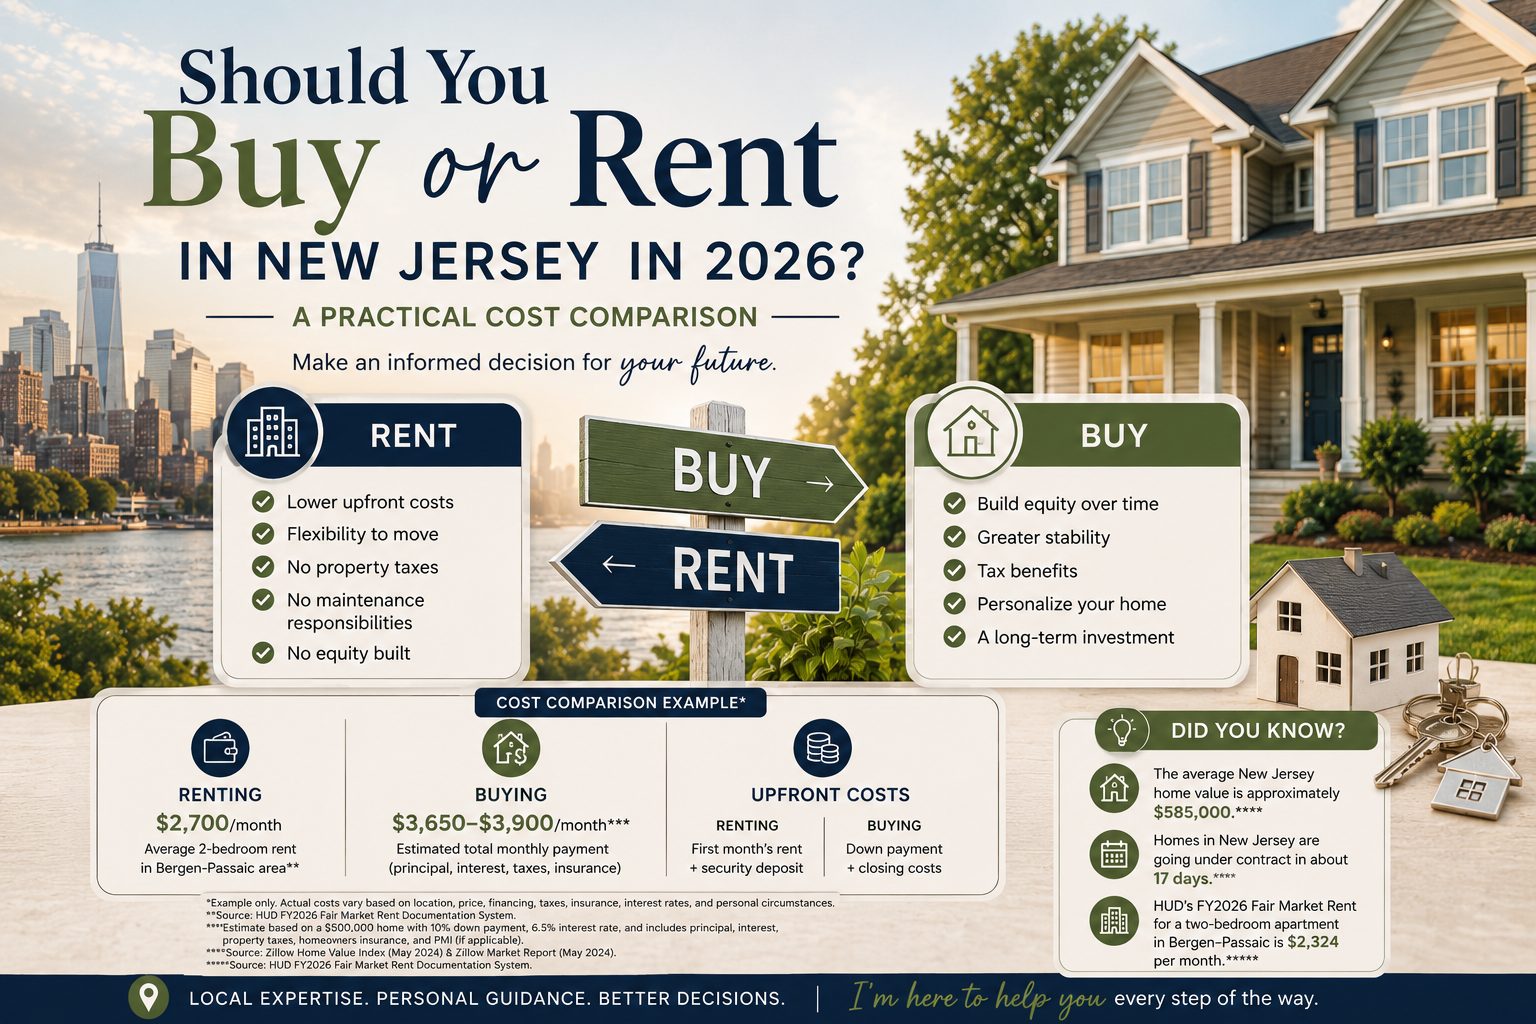
Should You Buy or Rent in New Jersey in 2026? A Practical Cost Comparison
For many people, one of the biggest financial questions isn’t which home to buy—it’s whether buying is the right choice at all.
New Jersey offers incredible communities, excellent schools, convenient transportation, and diverse housing options. However, it also comes with higher home prices, property taxes, and living expenses than many other states.
So, is buying still worth it in 2026?
The answer depends on your financial situation, your goals, and how long you plan to stay. This guide will help you compare the real costs of renting and buying so you can make an informed decision.
Why This Question Matters More Than Ever
The housing market has changed over the last few years. Mortgage rates, home prices, and rental costs have all increased compared to previous years.
Many renters wonder if they should keep renting until prices fall, while many buyers worry about purchasing at the wrong time.
Instead of trying to perfectly time the market, it often makes more sense to evaluate your own financial readiness. The best time to buy is when you are financially prepared and purchasing aligns with your long-term goals.
The Real Cost of Renting in New Jersey
Renting offers flexibility, especially if you’re not ready to settle in one location or expect major life changes.
Advantages include:
- Lower upfront costs
- Minimal maintenance responsibilities
- Easier relocation
- No property tax obligations
- Predictable monthly housing expenses
However, renting also has long-term tradeoffs.
Monthly rent payments build no home equity, and lease renewals often bring rent increases. Over several years, renters may spend tens of thousands of dollars without building ownership in a property.
For people planning to stay in New Jersey for several years, it’s worth comparing the long-term financial impact of renting versus owning.
The True Cost of Buying a Home
Homeownership involves more than a monthly mortgage payment.
Buyers should budget for:
- Down payment
- Closing costs
- Property taxes
- Homeowners insurance
- Maintenance and repairs
- Utilities
- HOA fees (if applicable)
Although these costs can seem significant, each mortgage payment generally helps build equity over time. As you pay down your loan and if your home’s value increases, you may build wealth that renting does not provide.
For many families, homeownership also offers greater stability and the freedom to personalize their living space.
When Renting Makes Financial Sense
Renting may be the better option if:
- You’re planning to move within the next few years.
- Your employment situation is uncertain.
- You’re building your emergency savings.
- You’re working on improving your credit.
- You’re paying down high-interest debt.
- You’re exploring different New Jersey communities before committing.
There’s no shame in renting while preparing for homeownership. Taking time to strengthen your financial foundation can make the buying process much smoother later.
When Buying May Be the Smarter Long-Term Move
Buying may be a strong choice if you:
- Plan to stay in the area for several years.
- Have stable income.
- Have money saved for your down payment and closing costs.
- Can comfortably afford the monthly payment.
- Want to build equity over time.
- Value long-term housing stability.
Owning a home isn’t just about financial investment—it can also provide a sense of permanence, community, and pride of ownership.
Hidden Costs Many People Overlook
Whether you rent or buy, it’s important to consider expenses beyond the monthly payment.
Renters may encounter:
- Annual rent increases
- Security deposits
- Renter’s insurance
- Moving costs
- Pet fees
- Parking or amenity fees
Homeowners may face:
- Unexpected repairs
- Appliance replacements
- Landscaping
- Snow removal
- Higher utility costs
- Home maintenance projects
Planning for these additional expenses helps reduce financial surprises.
Questions to Ask Yourself Before Deciding
Ask yourself:
- How long do I expect to stay in New Jersey?
- Do I have an emergency fund?
- Can I comfortably afford monthly housing costs?
- Is my job stable?
- Do I want the flexibility of renting or the stability of owning?
- Am I prepared for maintenance responsibilities?
These questions can provide valuable insight into which option best fits your current stage of life.
How a Local Real Estate Professional Can Help
Every buyer’s situation is different.
A local real estate professional can help you understand current market conditions, estimate monthly ownership costs, explain available financing options, and compare neighborhoods that match your lifestyle and budget.
Even if you’re not ready to buy today, having a conversation can help you create a realistic plan for the future.
Final Thoughts
There isn’t a universal answer to the question of whether buying or renting is better.
For some people, renting provides the flexibility they need right now. For others, buying offers the opportunity to build equity and establish long-term roots in the community.
The key is making a decision based on your personal financial situation and future goals—not simply on market headlines or what others are doing.
Whether you’re considering your first home or simply exploring your options, taking time to understand the numbers can help you move forward with confidence.
Example: Renting vs. Buying in New Jersey
Example only. Actual costs vary based on location, price, financing, taxes, insurance, and interest rates.
| Expense | Renting | Buying |
|---|---|---|
| Monthly Housing Payment | $2,700 | ~$3,650 |
| Upfront Costs | First month’s rent + security deposit | Down payment + closing costs |
| Maintenance | Usually covered by landlord | Paid by homeowner |
| Property Taxes | Included in rent | Included in monthly payment (if escrowed) |
| Equity | $0 | Builds over time |
| Ability to Customize | Limited | Full control |
A monthly mortgage payment on a median-priced New Jersey home can be considerably higher than rent today because of home prices, mortgage rates, taxes, and insurance. However, homeowners gradually build equity as they pay down their mortgage, while renters do not build ownership through their monthly payments.
Where Does Your Monthly Payment Go?
Imagine two families who each spend about $2,700 per month on housing.
Family A: Renting
- Monthly rent: $2,700
- Annual housing cost:
$32,400 - Equity after 5 years:
$0
They’ve had flexibility and avoided many maintenance responsibilities, but none of their rent payments created ownership.
Family B: Buying
Suppose they purchase a home.
- Purchase price: $500,000
- Down payment: 10% ($50,000)
- Mortgage: $450,000
- Estimated monthly housing payment (including principal, interest, taxes, insurance, and assuming typical costs): around $3,600–$3,900
Part of every mortgage payment reduces the loan balance, increasing the homeowner’s equity over time. If home values also appreciate, equity may grow even further, although appreciation is never guaranteed.
A Five-Year Snapshot
| After 5 Years | Renting | Buying |
|---|---|---|
| Housing Payments Made | ~$162,000 | Higher monthly cost |
| Home Equity | $0 | Potentially tens of thousands of dollars (depending on loan payoff and market performance) |
| Flexibility | High | Lower |
| Stability | Depends on lease renewals | Greater long-term stability |
Remember: Buying is not automatically the better financial decision. If you expect to move within a few years, renting may be the more practical and cost-effective choice.
——————————————————————————————————————————————————–
Did You Know?
- The average New Jersey home value is approximately $585,000.
- Homes in New Jersey are going under contract in about 17 days, reflecting continued buyer demand in many markets.
- In the Bergen–Passaic area, HUD’s FY2026 Fair Market Rent for a two-bedroom apartment is $2,324 per month, though many market-rate rentals lease for more depending on the community and amenities.
| If Your Household Income Is… | You Might Consider… |
|---|---|
| $75,000–$100,000 | Condo or starter home (depending on area and financing) |
| $100,000–$150,000 | More options in many NJ communities |
| $150,000+ | Wider selection, depending on debt, down payment, and location |
Please consider that purchasing power depends on credit score, existing debt, down payment, interest rates, taxes, insurance, and lender guidelines—not income alone.
Thinking about buying your first home or wondering if now is the right time?
I’d be happy to help you compare the costs of renting versus buying based on your unique financial situation and goals. Whether you’re ready to purchase soon or simply planning for the future, having accurate information is the first step.
Let’s connect and create a personalized plan that works for you.
Regis De la Cruz
New Jersey Real Estate Professional
Helping you find Where you Belong
This article is for general educational purposes and is not financial, mortgage, tax, or legal advice. Mortgage programs, assistance programs, market conditions, and eligibility requirements can change. Consult the appropriate licensed professionals regarding your individual situation.
