
 Facebook
 X
 Pinterest
 Copy Link
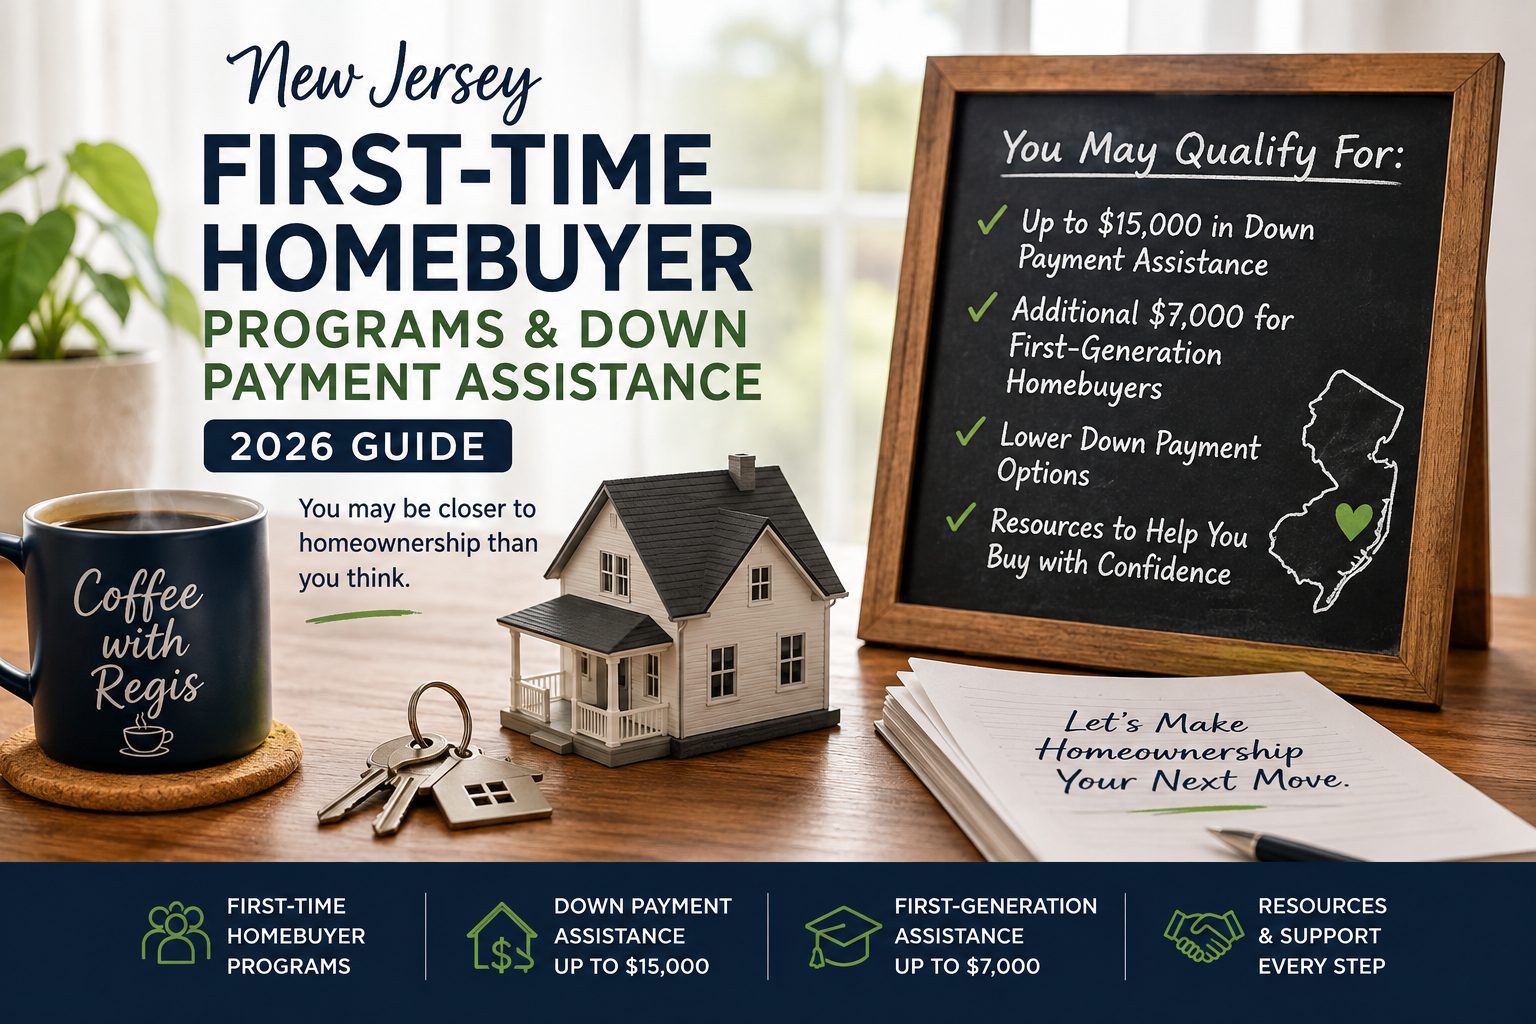
☕ Coffee with Regis
Imagine we’re sitting together at a local coffee shop in Elmwood Park.
You ask…
I want to buy a home in New Jersey, but I don’t have a big down payment. Can I still buy?
This is one of the questions I hear from people who want to become homeowners but believe the down payment is standing in their way. Here’s what I’d tell you…
Buying a home in New Jersey may feel out of reach when you’re worried about the down payment, closing costs, or whether you can qualify for a mortgage.
But here’s something many buyers don’t realize:
You may not need 20% down to buy a home—and qualified New Jersey buyers may have access to programs that can help with down payment and closing costs.
The key is knowing which programs exist and finding out whether you qualify before you start seriously shopping for a home.
This simple guide explains some of the options available to New Jersey homebuyers in 2026 and where to start.
Quick Answer: Does New Jersey Help First-Time Homebuyers?
Yes. The New Jersey Housing and Mortgage Finance Agency (NJHMFA) offers mortgage and down payment assistance programs for qualified buyers.
NJHMFA’s statewide Down Payment Assistance Program currently provides eligible first-time homebuyers with up to $15,000 toward down payment and closing costs, depending on the county where the property is located.
Qualified first-generation homebuyers may receive an additional $7,000, bringing potential total assistance to $17,000–$22,000, depending on the applicable county and eligibility requirements.
Programs have specific requirements, so not every buyer will qualify.
1. Who Is Considered a First-Time Homebuyer in New Jersey?
Here’s the first surprise:
You don’t necessarily have to be buying a home for the first time in your life.
For NJHMFA programs, you are generally considered a first-time homebuyer if you have not owned a home during the previous three years.
The home you’re purchasing must generally be in New Jersey and used as your primary residence.
There are additional requirements and exceptions depending on the program.
Why does first-time buyer status matter?
It may help you qualify for:
- Down payment assistance
- Closing cost assistance
- Special mortgage programs
- Lower down payment options
Regis’ Buyer Tip: Don’t assume you don’t qualify because you’ve owned property before. Ask an NJHMFA participating lender to review your specific situation.
2. How Much Down Payment Assistance Is Available in New Jersey?
This is probably the question you’re really here to answer.
NJHMFA Down Payment Assistance Program
Qualified first-time homebuyers may currently receive up to $15,000, based on the county where the property is being purchased.
The money can be used toward:
- Your down payment
- Eligible closing costs
The assistance is structured as an interest-free, five-year forgivable second loan with no monthly payment.
However, there are important conditions.
For example, NJHMFA states that a buyer generally must remain in the home for the required five-year period without moving or refinancing for the assistance to be forgiven.
That’s why it’s important to understand the program before deciding whether it’s right for you.
3. What Is New Jersey’s First-Generation Homebuyer Assistance?
New Jersey also has additional assistance for certain first-generation homebuyers.
Qualified buyers may receive an additional:
$7,000
This assistance can be combined with NJHMFA’s regular Down Payment Assistance Program.
That means a qualified buyer could potentially receive:
| NJHMFA Assistance | Potential Amount |
|---|---|
| Standard Down Payment Assistance | Up to $15,000 |
| Additional First-Generation Assistance | $7,000 |
| Potential Combined Assistance | $17,000–$22,000 |
The actual amount depends on the county, program, and buyer’s eligibility.
4. What Does “First-Generation Homebuyer” Mean?
This is different from simply being a first-time buyer.
NJHMFA has specific rules defining who qualifies as a first-generation homebuyer.
Generally, the program looks at factors including whether your parents or legal guardians currently own residential real estate and the homeownership history of you and other members of your household.
Certain individuals who have been in New Jersey foster care may also qualify under the program.
Because the definition is detailed, don’t try to determine eligibility based only on a short online description.
Ask an NJHMFA participating lender to determine whether you meet the current requirements.
5. Do You Have to Pay the Down Payment Assistance Back?
This is an important question.
NJHMFA’s Down Payment Assistance is generally structured as an:
Interest-free, five-year forgivable second loan with no monthly payment.
“Forgivable” doesn’t mean there are no conditions.
NJHMFA explains that the home must remain your residence for the required period and that moving or refinancing during that period can affect forgiveness.
Before accepting assistance, make sure you understand:
- How long you must live in the home
- What happens if you sell
- What happens if you refinance
- What happens if you move
- When the assistance becomes fully forgiven
Your lender can explain how these rules apply to you.
6. What Mortgage Goes With NJHMFA Assistance?
The down payment assistance isn’t simply a check that can be used with any mortgage.
NJHMFA requires its DPA to be paired with an eligible NJHMFA first mortgage through a participating lender.
NJHMFA offers different mortgage options, including its First-Time Homebuyer Mortgage Program and HFA Advantage Mortgage Program.
Depending on the program and your qualifications, financing may involve conventional or government-insured mortgage options.
This is why choosing the right lender matters.
7. How Do You Qualify?
Qualification depends on the specific program.
NJHMFA requirements can include:
- First-time homebuyer status
- Household income
- Purchase price
- Property location
- Mortgage qualifications
- Primary-residence requirements
- Program-specific credit and debt requirements
The home must generally be located in New Jersey and become your primary residence.
Important:
Don’t eliminate yourself before talking to someone who understands the programs.
You may have more options than you realize.
8. What If You Don’t Have a Large Down Payment?
This is where I want first-time buyers to pay attention.
One of the biggest myths about buying a home is:
“I need 20% down.”
You don’t necessarily need 20%.
Depending on your qualifications, mortgage options can include:
Conventional Financing
Certain conventional programs may allow qualified buyers to purchase with a relatively low down payment.
FHA Financing
FHA-insured mortgages can offer lower down payment requirements for eligible borrowers.
VA Financing
Eligible veterans, active-duty service members, and certain surviving spouses may have access to VA financing, which can offer significant benefits.
USDA Financing
Eligible buyers purchasing qualifying properties may have access to USDA financing.
NJHMFA Programs
Eligible buyers may be able to combine certain NJHMFA mortgages with down payment assistance.
The best program isn’t necessarily the one requiring the least money upfront.
Ask your lender to compare the monthly payment, mortgage insurance, interest rate, cash needed at closing, and long-term costs.
9. What About Closing Costs?
Your down payment isn’t the only money you’ll need.
Closing costs can include expenses associated with:
- Mortgage financing
- Appraisal
- Title services
- Attorney services
- Homeowners insurance
- Property taxes and prepaid items
- Other transaction-related expenses
The exact amount varies significantly from one transaction to another.
That’s why I encourage buyers to ask their lender a better question than:
“How much down payment do I need?”
Ask:
“Approximately how much cash will I need to close?”
That gives you a much more complete picture.
10. What If You’re Not Ready to Buy Yet?
That’s okay.
You don’t need to wait until everything is perfect before learning about your options.
Maybe you need to:
- Improve your credit
- Reduce some debt
- Save additional money
- Establish employment history
- Understand your budget
- Explore assistance programs
Finding this out before you fall in love with a house gives you time to create a plan.
Sometimes your first step toward homeownership isn’t touring a house.
It’s finding out what you need to do to become ready.
11. Where Should You Start?
NJHMFA provides a simple home-buying roadmap.
The process generally includes:
- Learn about the home-buying process.
- Connect with an NJHMFA participating lender.
- Determine which programs you may qualify for.
- Complete required homebuyer education or counseling.
- Find a home.
- Complete mortgage processing and underwriting.
- Close and receive your keys.
You don’t need to understand every step today.
You just need to start with Step One.
12. Official New Jersey Homebuyer Resources
For current program requirements, always use official sources.
New Jersey Housing and Mortgage Finance Agency (NJHMFA)
Learn about mortgage programs and down payment assistance.
NJHMFA Participating Lenders
Connect with lenders approved to originate NJHMFA programs.
HUD-Approved Housing Counseling
Housing counselors can help buyers understand budgeting, credit, mortgage readiness, and the home-buying process.
Program requirements and availability can change, so always verify current information before making a financial decision.
Frequently Asked Questions
How much down payment assistance can I get in New Jersey?
Qualified first-time buyers may currently receive up to $15,000 through NJHMFA’s Down Payment Assistance Program, depending on the county. Qualified first-generation buyers may be eligible for an additional $7,000.
Can I get $22,000 toward buying a home in New Jersey?
Potentially. NJHMFA currently states that qualified buyers combining applicable down payment assistance with first-generation assistance may receive total assistance of $17,000 to $22,000. Eligibility requirements apply.
Do I need 20% down to buy a house in New Jersey?
No. Several mortgage programs may allow qualified buyers to purchase with less than 20% down.
Can down payment assistance also help with closing costs?
NJHMFA states that its DPA can be used by qualified buyers toward eligible down payment and closing costs, subject to program requirements.
Do I have to repay NJHMFA down payment assistance?
NJHMFA’s DPA is structured as an interest-free, five-year forgivable second loan with no monthly payment. Conditions apply, including requirements related to occupying the property and the five-year forgiveness period.
What credit score do I need?
Credit requirements depend on the mortgage program. Instead of assuming you don’t qualify, speak with a participating lender who can evaluate your complete financial situation.
Can I qualify if I owned a home years ago?
Possibly. NJHMFA generally considers someone a first-time homebuyer if they haven’t owned a home during the previous three years. Program-specific rules and exceptions apply.
You May Be Closer to Homeownership Than You Think
If the down payment or closing costs are what’s keeping you from exploring homeownership, don’t assume you can’t buy.
Find out first.
The goal isn’t to convince you to purchase a home before you’re ready.
The goal is to help you understand:
Where are you today?
What programs might be available to you?
What can you comfortably afford?
And what should your next step be?
Once you know those answers, you can make an informed decision.
Need Help Getting Started?
If you’re thinking about buying a home in New Jersey but don’t know where to begin, contact me.
I’ll help you understand the home-buying process, identify the questions you should be asking, and guide you toward the appropriate professionals and resources for your situation.
You don’t need to have everything figured out before reaching out.
Sometimes the first conversation is simply about creating a plan.
Regis De la Cruz
New Jersey Real Estate Professional
Helping you find where you belong
This article is provided for general educational purposes only and does not constitute mortgage, financial, tax, or legal advice. Mortgage products, assistance amounts, interest rates, eligibility requirements, and program availability can change. Verify current information with NJHMFA and appropriately licensed professionals before making financial decisions.
